Insurance vs. Cash Price: Why Your Prescription May Have Two Different Prices
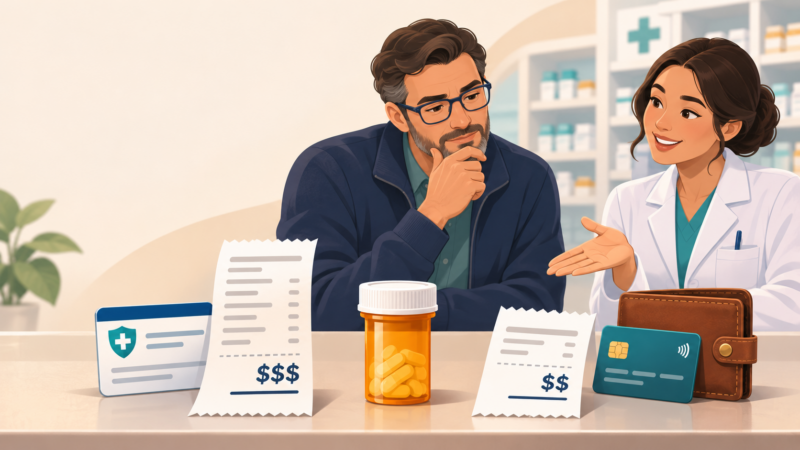
Insurance vs. Cash Price: Why Your Prescription May Have Two Different Prices
Using insurance doesn’t always produce the lowest pharmacy bill. Here’s how to compare your options—and understand the trade-offs before you pay.
You hand over your insurance card, wait for the pharmacy to process your prescription, and hear the total: $35.
Then you ask what the medication would cost without insurance. The answer is $18.
Same prescription. Same quantity. Same pharmacy. Two different prices.
These numbers are an illustration, but the situation raises a reasonable question: Why would someone with insurance pay more?
The answer is that your insurance benefit and the pharmacy’s cash or discount pricing follow different rules. Understanding those rules can help you make a better decision at your next refill.
What does the “insurance price” actually mean?
When you ask what a prescription costs through insurance, the number you usually hear is your share of the bill, rather than the total amount the pharmacy receives.
Your share may depend on:
- Your deductible: What you must pay for certain covered services before your plan starts contributing.
- Your copayment: A set amount for a covered prescription.
- Your coinsurance: A percentage of the covered cost.
- Your drug’s formulary tier: Its category on your plan’s covered medication list.
- Your pharmacy network: Which pharmacies your plan covers and whether it offers preferred pricing.
Some plans have a separate prescription deductible. Others cover certain medications before you meet the deductible. Your benefit documents explain which rules apply.
This means “my insurance covers it” doesn’t tell you exactly what you will pay. You still need a quote for your specific medication, quantity and pharmacy.
What is the cash price?
The cash price is generally the amount you pay when the prescription is purchased outside your insurance benefit. “Cash” describes how the purchase is processed; it doesn’t necessarily mean paying with paper money.
However, people often use “cash price” to describe several different offers:
| Price type | What it means |
|---|---|
| Standard cash price | The pharmacy’s price without insurance or a separate discount program |
| Discount-card price | A price available through a participating prescription discount program |
| Membership price | A price available through a pharmacy or paid membership program |
| Insurance cost | Your responsibility when the prescription is processed through your plan |
These prices can differ. A coupon quote is not necessarily the pharmacy’s standard cash price, and a membership offer may carry a separate fee. Ask which price you are being shown.
Why can paying without insurance cost less?
Your insurance cost and a cash or discount offer are calculated through different arrangements.
For example, your plan may require a particular copayment for a drug, while a separate pharmacy program offers a lower price. Or you may still be responsible for the covered cost because you haven’t met your deductible.
A medication’s coverage category also matters. A drug that is less favorably covered—or excluded from your plan—may have an outside-insurance discount worth comparing. GoodRx, for example, explicitly allows people with insurance to use its discount instead when the price is lower.
The reverse can also happen: your insurance benefit may be substantially cheaper than any cash offer.
Having insurance is a reason to check your benefit, not a reason to skip comparing prices.
A simple example: $35 versus $18
Imagine these quotes for the same 30-day prescription:
| Payment option | Amount due |
|---|---|
| Through insurance | $35 |
| Standard cash price | $42 |
| Participating discount program | $18 |
Hypothetical prices for illustration only.
The discount option saves $17 on this fill. If the same difference applied to 12 monthly fills, the immediate savings would total $204.
But that calculation leaves out another question: Will the purchase count toward your insurance spending requirements?
The deductible trade-off: today’s savings versus the year ahead
A purchase made outside insurance may not count toward your deductible or annual out-of-pocket limit.
For commercial coverage, ask your insurer whether it allows any credit or reimbursement for the specific purchase, what documentation is required, and whether a discount-program transaction qualifies. Don’t assume that keeping a receipt automatically earns credit.
For Medicare, the guidance is explicit: purchases made using discount cards instead of your Medicare drug plan do not count toward your Medicare deductible or out-of-pocket maximum.
That distinction can affect the value of the lower price.
If you expect modest covered expenses throughout the year, immediate savings may be especially useful. If you anticipate substantial covered expenses, spending that counts toward your plan’s limits may affect your total annual cost.
There is no universal answer. A deductible credit also isn’t the same as getting money back—it matters only in the context of your plan and the care you expect to use.
Before deciding, ask your insurer:
“If I buy this prescription outside my insurance, will any of that payment count toward my deductible or out-of-pocket maximum? What would I need to submit?”
Can you combine a discount card with insurance?
For a typical prescription discount card, you generally choose the card price or your insurance benefit for that fill.
GoodRx, for example, states that its discounts cannot be combined with insurance, Medicare or Medicaid. Tell the pharmacist which option you want before the transaction is finalized.
Manufacturer copay assistance is a different type of program. Some manufacturer cards work alongside eligible commercial insurance, subject to restrictions, savings limits and expiration dates. Government coverage exclusions commonly apply, and whether assistance counts toward plan spending limits can vary. Read the specific program terms rather than treating every “coupon” as interchangeable.
How to make a fair price comparison
A lower advertised number is useful only if it matches what you need.
Before comparing quotes, confirm:
- The exact medication and whether the quote is for a brand or generic.
- The prescribed strength.
- The dosage form, including any extended-release formulation.
- The quantity and number of days supplied.
- Shipping, handling or membership charges.
- Any eligibility requirements or limits on repeat purchases.
A quote for 30 tablets cannot be compared directly with one for 90 tablets. Likewise, different strengths or formulations should not be treated as interchangeable without confirmation from your pharmacist or prescriber.
Use the Prescription Cost Comparison tool to organize equivalent quotes and include additional charges.
Does mail order change the calculation?
Mail order is another option to compare, rather than an automatic guarantee of savings.
Start by asking your insurer whether it covers mail-order prescriptions and which pharmacies participate. Then compare the covered mail-order cost with an equivalent local pharmacy quote and any cash-pay offer. HealthCare.gov recommends checking pharmacy networks and asking whether prescription delivery is available under your plan.
For a 90-day supply, compare the total against three equivalent 30-day fills. Include delivery costs and check when payment is due.
Also consider whether a larger supply makes sense for your situation. If your prescriber is still adjusting treatment, ask whether ordering several months at once is appropriate.
What if the high price is really a coverage problem?
An unexpectedly expensive prescription may deserve a benefits check before you decide to pay outside insurance.
Ask the pharmacy whether the quote reflects:
- Your correct insurance information.
- An unmet deductible.
- A nonpreferred or noncovered medication.
- A pharmacy outside your plan’s network.
- A coverage requirement that needs follow-up.
If your plan doesn’t cover the prescribed medication, ask about its exceptions process. HealthCare.gov explains that patients may request an exception and appeal a denial; the prescriber may need to explain why the medication is appropriate.
A cash quote can help you understand your options, but it doesn’t resolve the underlying coverage issue.
Five questions to ask before you pay
You don’t need to understand every part of prescription pricing to start a useful conversation.
Ask your pharmacist:
- “What will I pay through my insurance today?”
- “What is your price without insurance for this exact prescription?”
- “Is there a discount option, and what are its conditions?”
- “Would the price change at a different covered quantity or participating pharmacy?”
- “Is there an insurance issue I should resolve before paying?”
Then confirm deductible and out-of-pocket credit questions directly with your insurer.
Keep your receipt, note how the prescription was processed, and compare again when your benefits, medication or quoted price changes.
Ask for both prices—and understand what each buys you
Insurance can provide valuable prescription coverage. Cash and discount programs can sometimes offer a lower price for an individual fill. The most useful comparison considers both the amount due today and how the purchase affects your coverage over the year.
Before your next refill, ask for both prices. Then check what counts toward your plan.
Visit our Prescription Savings guide and free prescription tools to prepare your comparison.
This article provides general education about U.S. prescription payment options. Benefits and program terms vary. Confirm your coverage with your insurer and medication questions with your pharmacist or prescriber.